Who Owns the GEO/AEO Agencies? The 2026 Ownership Map
Generative engine optimization (GEO), also called answer engine optimization (AEO), was a boutique service in 2023. Three years later it sits inside the world's largest holding companies, private equity roll-ups, and a growing field of founder-run specialists, and the ownership behind an agency now shapes how it sells, prices, and staffs the work.
Our research team mapped 61 agencies with a live GEO/AEO offering by who owns them and how large they are. Below are the ownership map, the split by owner type and agency size, the holding companies and private equity sponsors behind each agency, a timeline of the deals, and what each ownership model means for a company hiring a GEO/AEO partner.
The GEO/AEO Agency Ownership Universe
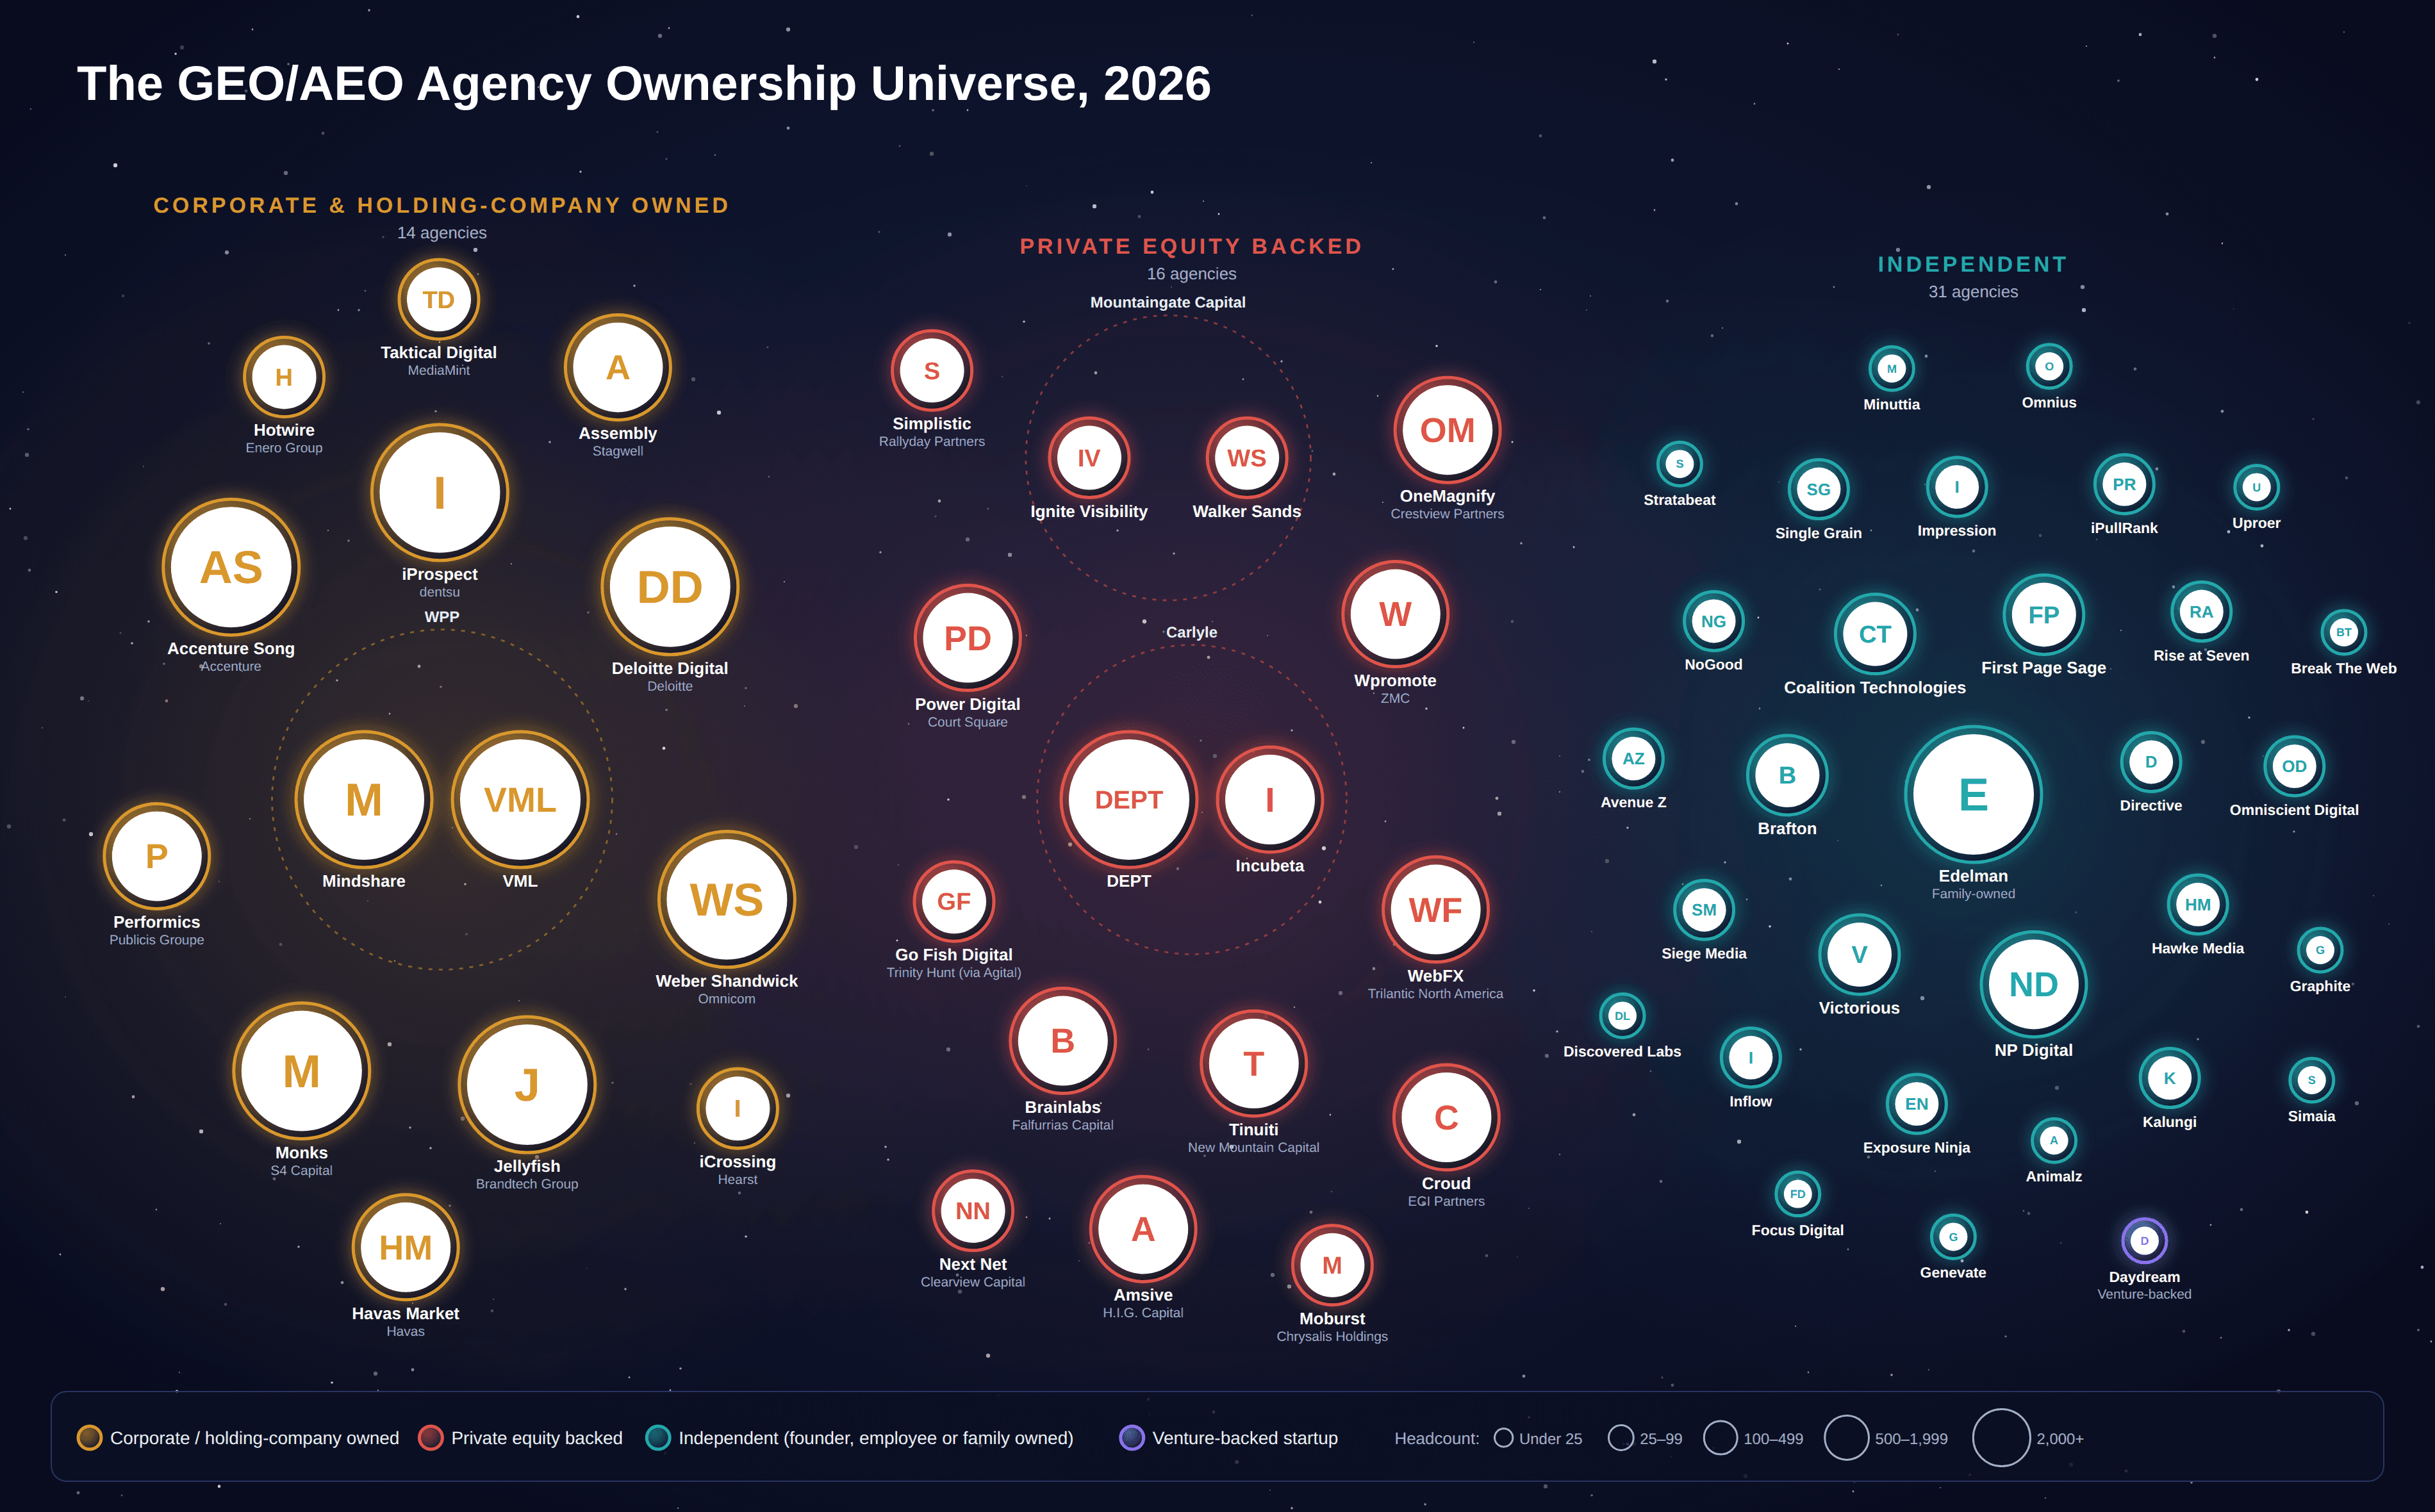
The map below places each agency in one of three galaxies: corporate and holding-company owned, private equity backed, and independent. Planet size reflects approximate headcount, and dashed rings group agencies that share an owner.
The Ownership Split at a Glance
Independent agencies and one venture-backed startup make up just over half of the map, but the corporate and private equity galaxies hold most of the headcount. The table below summarizes each ownership type.
| Ownership Type | Agencies | Share of Map | Median Headcount Band | Examples |
|---|---|---|---|---|
| Corporate or holding-company owned | 14 | 23.0% | 2,000 and above | iProspect, Jellyfish, Monks |
| Private equity backed | 16 | 26.2% | 500 to 1,999 | DEPT, Tinuiti, Brainlabs |
| Independent | 30 | 49.2% | 25 to 99 | Edelman, NP Digital, First Page Sage |
| Venture-backed startup | 1 | 1.6% | Under 25 | Daydream |
| All agencies | 61 | 100.0% | 100 to 499 |
Three findings stand out from the split:
- We found that 31 of the 61 agencies, or 50.8%, are independent or venture-backed. The other 30 are owned by a holding company, a corporate parent, or a private equity sponsor.
- Our data showed a sharp size gap between the three galaxies. The median corporate-owned agency sits in the 2,000-and-above headcount band, the median private equity backed agency in the 500 to 1,999 band, and the median independent in the 25 to 99 band.
- We observed that GEO/AEO is a practice line at almost every corporate and private equity owned agency on the map, while it is the core offering at many of the independents, particularly those founded or repositioned since 2023.
Ownership by Agency Size
Crossing ownership type with headcount band shows where each ownership model concentrates. Darker cells hold more agencies.
| Headcount Band | Corporate | Private Equity | Independent | Venture-Backed | Total |
|---|---|---|---|---|---|
| 2,000 and above | 8 | 1 | 1 | 0 | 10 |
| 500 to 1,999 | 3 | 9 | 1 | 0 | 13 |
| 100 to 499 | 3 | 6 | 4 | 0 | 13 |
| 25 to 99 | 0 | 0 | 13 | 0 | 13 |
| Under 25 | 0 | 0 | 11 | 1 | 12 |
| Total | 14 | 16 | 30 | 1 | 61 |
The size data points to three patterns:
- We found that every agency on the map with fewer than 100 employees is independent or venture-backed, 25 agencies in all. Neither holding companies nor private equity sponsors own a GEO/AEO agency below that size in our dataset.
- Our data showed that 8 of the 10 agencies with 2,000 or more employees are corporate-owned. The exceptions are DEPT, backed by Carlyle, and Edelman, which remains family-owned.
- We observed that private equity clusters in the middle. Nine of the 16 private equity backed agencies fall in the 500 to 1,999 band, the size at which performance agencies have historically attracted sponsor capital.
The Holding Companies and Corporate Parents
Fourteen agencies on the map belong to a holding company or corporate parent. Several sell GEO/AEO under a named product rather than as a stand-alone service.
| Parent | Agency | Headcount Band | How GEO/AEO Is Packaged |
|---|---|---|---|
| dentsu | iProspect | 2,000 and above | Search experience and GEO practice within performance media |
| Brandtech Group | Jellyfish | 2,000 and above | Share of Model platform and a dedicated GEO practice; acquired in June 2023 |
| WPP | Mindshare, VML | 2,000 and above | AI search guidance at Mindshare; GEO audits at VML |
| Omnicom | Weber Shandwick | 2,000 and above | Weber I/O AI visibility services; joined Omnicom with the Interpublic close in November 2025 |
| S4 Capital | Monks | 2,000 and above | AEO/GEO playbook and AI search services |
| Accenture | Accenture Song | 2,000 and above | Combined SEO and GEO teams |
| Deloitte | Deloitte Digital | 2,000 and above | Generative Experience Optimization methodology |
| Publicis Groupe | Performics | 500 to 1,999 | GEO within SEO and performance programs |
| Stagwell | Assembly | 500 to 1,999 | Stagwell Search+ agentic AI search platform |
| Havas | Havas Market | 500 to 1,999 | Dedicated GEO service line |
| Enero Group | Hotwire | 100 to 499 | Hotwire Radiate, GEO sold as a service |
| Hearst | iCrossing | 100 to 499 | Answer engine optimization practice |
| MediaMint | Taktical Digital | 100 to 499 | AI search and SEO services |
From the corporate data, three observations:
- We found that WPP is the only parent with two agencies on the map, Mindshare and VML, and that Omnicom, WPP, Publicis Groupe, dentsu, and Havas each own at least one agency selling GEO/AEO.
- Our data showed that corporate owners favor branded platforms. Jellyfish's Share of Model, Assembly's Stagwell Search+, and Hotwire's Radiate each turn GEO/AEO into a named product that can be bundled into larger media or communications contracts.
- We observed that Omnicom's acquisition of Interpublic, completed on November 26, 2025, moved Weber Shandwick and the rest of the former IPG network under a single parent, the largest ownership change on the corporate side of the map.
The Private Equity Sponsors
Sixteen agencies are backed by private equity or private investment firms. The table below lists each sponsor and the year its investment was announced, where public.
| Sponsor | Agency | Investment Year | Headcount Band |
|---|---|---|---|
| H.I.G. Capital | Amsive | Not disclosed | 500 to 1,999 |
| Crestview Partners | OneMagnify | Not disclosed | 500 to 1,999 |
| Clearview Capital | Next Net | Not disclosed | 100 to 499 |
| Rallyday Partners | Simplistic | Not disclosed | 100 to 499 |
| Carlyle | DEPT | 2021 | 2,000 and above |
| New Mountain Capital | Tinuiti | 2021 | 500 to 1,999 |
| Trilantic North America | WebFX | 2021 | 500 to 1,999 |
| Carlyle | Incubeta | 2022 | 500 to 1,999 |
| ZMC | Wpromote | 2022 | 500 to 1,999 |
| Court Square | Power Digital | 2022 | 500 to 1,999 |
| Falfurrias Capital | Brainlabs | 2023 | 500 to 1,999 |
| Mountaingate Capital | Ignite Visibility | 2023 | 100 to 499 |
| ECI Partners | Croud | 2024 | 500 to 1,999 |
| Trinity Hunt (via Agital) | Go Fish Digital | 2024 | 100 to 499 |
| Mountaingate Capital | Walker Sands | 2025 | 100 to 499 |
| Chrysalis Holdings | Moburst | 2026 | 100 to 499 |
Three findings stand out among the sponsors:
- We found that two sponsors hold more than one GEO/AEO agency. Carlyle backs DEPT and Incubeta, and Mountaingate Capital backs Ignite Visibility, since 2023, and Walker Sands, since October 2025.
- Our data showed that at least 6 of the 16 investments date from 2021 or 2022. At the four to six year hold periods typical of private equity, those positions are approaching the window in which sponsors usually look to sell or recapitalize.
- We observed that sponsor interest has continued into the AI search era. Walker Sands took a majority investment from Mountaingate Capital in October 2025, and Moburst took an $11.8 million equity investment from Chrysalis Holdings in May 2026, with the stated aim of funding acquisitions and AI capability.
Deal Timeline, 2021 to 2026
The grid below places each disclosed ownership event affecting an agency on the map in the year it was announced or closed.
| 2021 | 2022 | 2023 | 2024 | 2025 | 2026 |
|---|---|---|---|---|---|
| DEPT: Carlyle | Incubeta: Carlyle | Jellyfish: Brandtech | Go Fish Digital: Agital | Walker Sands: Mountaingate | Daydream: Series A |
| Tinuiti: New Mountain | Wpromote: ZMC | Brainlabs: Falfurrias | Croud: ECI Partners | Weber Shandwick: Omnicom | Moburst: Chrysalis |
| WebFX: Trilantic | Power Digital: Court Square | Ignite Visibility: Mountaingate | Simaia: pre-seed | ||
| Rise at Seven: MBO |
Shading follows the map: red for private equity, gold for corporate, teal for independent, violet for venture capital. MBO: management buyout.
The timeline shows two waves. The first, in 2021 and 2022, was a private equity build-out of performance and SEO agencies that later added GEO/AEO practices; the one exception that year, Rise at Seven's 2022 management buyout, moved ownership in the other direction, to a single founder. The second wave, from 2023 onward, is smaller and more varied: corporate consolidation at the top, targeted sponsor deals such as Walker Sands and Moburst, and the first venture rounds for AI-native GEO/AEO agencies.
The Independent Core
Thirty agencies on the map are independent, owned by founders, employees, or families, and one is a venture-backed startup. The independents range from Edelman, the largest independent PR firm, to GEO/AEO specialists with fewer than 25 staff.
| Agency | Ownership | Headcount Band |
|---|---|---|
| Edelman | Family-owned | 2,000 and above |
| NP Digital | Founder-owned | 500 to 1,999 |
| First Page Sage | Founder-owned | 100 to 499 |
| Coalition Technologies | Founder-owned | 100 to 499 |
| Victorious | Founder-owned | 100 to 499 |
| Brafton | Management-owned | 100 to 499 |
Three observations about the independents:
- We found that the specialist end of the market is almost entirely independent. First Page Sage, which introduced GEO as a commercial genre in 2023, remains founder-owned, as do iPullRank, Siege Media, and most of the agencies built around GEO/AEO from the start.
- Our data showed that ownership among independents takes several forms. Impression is employee-owned, Brafton, Inflow, and Animalz are led by management owners, and Edelman is family-owned.
- We observed that venture capital has begun to fund GEO/AEO agencies directly. Daydream raised a $15 million Series A in April 2026 led by WndrCo, First Round Capital, and Basis Set Ventures, and Simaia, which we classify as independent because it remains founder-led, raised pre-seed funding through Iterative's 2026 batch.
What Ownership Means for Buyers
Ownership does not determine quality, but it does shape how an agency behaves. Corporate-owned agencies tend to sell GEO/AEO as part of larger media, creative, or communications relationships, which can simplify procurement for large advertisers and make the service harder to buy on its own. Private equity backed agencies operate against growth and margin targets over a defined hold period, which often brings investment in tools and acquisitions along with the possibility of a sale during the engagement. Independent agencies are more likely to have their founders involved in client work and to treat GEO/AEO as the core product rather than a line extension, with less balance-sheet depth than the larger groups.
Buyers can ask any agency three questions that ownership makes relevant: who owns the firm and whether a sale or recapitalization is expected in the next 24 months, whether GEO/AEO is priced and staffed as its own service or bundled into a broader contract, and who on the team will do the work.
Methodology
We included agencies that publish a GEO, AEO, or AI search optimization service, product, or practice as of September 2026. Ownership was verified against press releases, sponsor portfolio pages, regulatory announcements, and company disclosures; minority growth investments are classified as private equity backed. Headcount bands are approximate, refer to the agency unit rather than its parent, and draw on company websites, published workforce data, and press coverage. Agencies whose ownership or offering could not be verified were excluded.
Requesting a Copy of This Report
The full dataset behind the map, including the ownership source for each agency, is available on request. You can reach out here.
Sources
- GEO/AEO Agency Ownership Study, Independent Research Team, September 2026, New York, New York.
- Omnicom Completes Acquisition of Interpublic. Omnicom Group, November 2025, New York, New York.
- The Brandtech Group. Brandtech Group, 2026, London, United Kingdom.
- Walker Sands Partners With Mountaingate Capital. Business Wire, October 2025, Chicago, Illinois.
- Carlyle Group Partners With Digital Agency DEPT. The Carlyle Group, 2021, Washington, D.C.
- Carlyle to Acquire International Marketing Agency Incubeta. The Carlyle Group, 2022, Washington, D.C.
- WebFX Announces Strategic Investment From Trilantic North America. Trilantic North America, October 2021, New York, New York.
- Power Digital Announces Strategic Capital Investment From Court Square Capital Partners. Business Wire, March 2022, San Diego, California.
- Monroe Capital Supports ZMC's Acquisition of Wpromote. Business Wire, December 2022, Chicago, Illinois.
- Livingbridge Signs Out of Brainlabs as Falfurrias Capital Logs In. PE Hub, 2023, United States.
- Amsive. H.I.G. Capital Portfolio, 2026, Miami, Florida.
- Current Investments. Crestview Partners, 2026, New York, New York.
- Investments. Clearview Capital, 2026, Stamford, Connecticut.
- Portfolio. Rallyday Partners, 2026, New York, New York.
- ECI Partners Acquires Majority Stake in Global Digital Marketing Agency. Insider Media, November 2024, United Kingdom.
- Moburst's Latest $11.8M Investment Round. Adweek, May 2026, New York, New York.
- Daydream Raises $15M to Build AI-Native SEO/AEO Agency. Citybiz, April 2026, United States.
- Hotwire Radiate Announcement. Business Wire, June 2025, London, United Kingdom.
- Edelman Introduces GEOsight. Edelman, May 2025, Chicago, Illinois.